Weekly sustainability insights can now be found by following this link: Sustainability Corner
Weekly Energy Industry Summary
Commodity Fundamentals
Week of November 2, 2026
- Prompt-month (December) natural gas settled at $2.86/MMbtu, down $.04, on Monday, November 2.
- Prompt-month crude (WTI) settled at $94.46/bbl., down $7.66 on Monday, November 2.
Natural Gas Fundamentals - Neutral/Bearish
- Bearish weather forecasts keep a lid on natural gas pricing action.
- October was the 4th warmest on record, dampening residential/commercial demand.
- Residential/commercial demand for natural gas, month-to-date, averaged 16.6 Bcf per day versus 22.8 one year ago.
- Power generation demand, month-to-date, averaged 31.4 Bcf per day versus 29 one year ago.
- LNG feedgas volumes month-to-date, averaged 19.4 Bcf per day versus 18.2 one year ago.
- Production of natural gas has fallen month-to-date to 107.7 Bcf per day, down 4 Bcf per day versus September as Appalachian producers respond to low basis pricing in the Marcellus and Haynesville shale plays.
- Storage inventories will be near 3.8 Tcf by end of next week, and the first week of November calls for an injection of gas, not a withdrawal.
- 2027-31 NYMEX strip prices are: $2.91, $3.57, $3.65, $3.65 and $3.62 respectively. The 2027 strip is trading at a four year low.

Crude Oil - Bullish
- Point of Clarification: The "Bullish" moniker above will remain in place until further notice as the situation in the Persian Gulf remains highly unstable.
- Prompt-month crude (WTI) settled at $96.46/bbl., down $7.66 on Monday, November 2.
- Crude dropped yesterday as the Trump Administration said that it wanted to give diplomacy "a last try" before resuming military strikes.
- Signs that crude supplies are flowing through and around the Strait of Hormuz are also weighing on oil prices as reports from third party tracking agencies say Saudi Arabia shipped an average of 7 million barrels per day from its east and west coasts in October.
- Global oil and refined product inventories remain under high pressure, that is, they are low.
- U.S. commercial crude oil stocks (not the SPR) are 411 million barrels, 4% below the five-year-average.

Economy - Neutral
- U.S. GDP grew at a 3.4% annualized rate in the third quarter, its fastest pace in a year. Consumer spending and AI investment were the primary drivers.
- September job openings rose by 330,000 to 7.52 million, exceeding economists' expectations. Hiring also increased, while layoffs declined.
- September payroll growth was weak at 29,000 highlighting a labor market that is holding up, but not generating a large number of new jobs.
- The September inflation numbers were not good, with the PCE index rising 3.6% year-over-year.
- The Federal Reserve kept interest rates steady at its latest meeting.
Weather - Neutral/Bearish
- A cold front crosses the nation's midsection today fueling strong storms and localized flooding. The front reaches the East Coast on Thursday bringing some much-needed rain. It will end the unseasonably warm air across the Eastern half of the country; however, with no cold air in the pattern to work with, next week looks cooler but very close to "seasonally normal" in the East while a warming trend begins in the Midwest.


Weekly Natural Gas Report
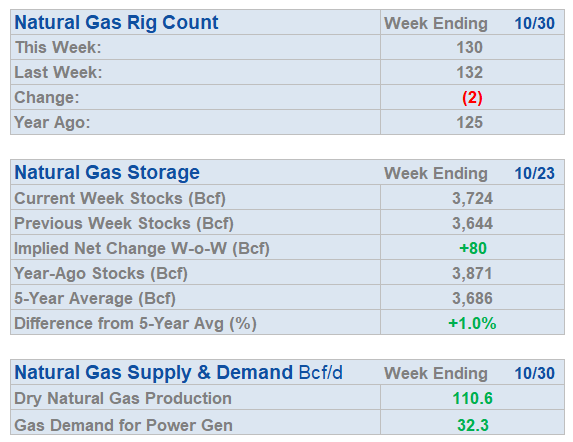
- Inventories of natural gas in underground storage for the week ending October 23 are 3,724 Bcf; an injection of 80 Bcf was reported for the week ending October 23. Stocks were 147 Bcf lower than this time last year and 38 Bcf above the five-year-average.



Weekly Power Report:


Mid-Atlantic Electric Summary
- The Mid-Atlantic Region’s forward power prices were slightly higher over the past week despite any significant heating or cooling demand, and despite an extension of the sell-off of the December gas contract due to warmer weather forecasts, a larger than average storage injection as well as gas production being strong. As we have noted in the past, the gas to power correlation has diverged considerably, in most Mid-Atlantic zones, due to the continued growth of data center electricity demand that continues to be priced into the market due to congestion risk. The forward electricity prices for the 2027-2031 calendar strips were 2% higher on average over the past week, with lower prices seen for 2027/28 terms and higher prices for the later terms 2029/31. The preliminary, day-ahead settlement price for October in West Hub is $68.19/MWh or is 1% higher than September’s final settlement price average of $67.85/MWh.
- PJM Submits Revisions to FERC on the Reliability Backstop Procurement (RBP) –PJM filed targeted revisions to the RBP mechanism to address concerns raised in FERC’s 9/29 order. The RBP is a one-time procurement mechanism designed to procure additional capacity in response to rapid large load growth across the region and is scheduled to commence on 3/1. In September, FERC largely accepted PJM’s proposed auction mechanics but raised concerns about cost allocation, transmission owner exit provisions, and load serving entities (LSEs) collateral requirements, inviting PJM to make changes in a further filing. In its new filing, PJM proposes to allocate RBP costs based on incremental large load growth between the 2026 actual summer peak and updated forecast 2028/29 peak; reduce the LSE collateral requirement from the previously proposed $1.5 million/MW to 40% of the net present value of total RBP payment obligations (up to $686,000/MW, if the RBP clears at the $555/MW-day weighted-average price cap); and require LSEs, rather than withdrawing transmission owners, to remain responsible for RBP charges after a transmission owner withdraws from PJM.


Great Lakes Electric Summary
- The Great Lakes Region’s forward power prices were slightly higher over the past week despite a lack of any significant heating or cooling demand, and despite an extension of the sell-off of the December gas contract due to warmer weather forecasts, a larger than average storage injection as well as strong gas production. As we have noted in the past, the gas to power correlation has diverged considerably in many GLR zones due to the continued growth associated with data center electricity demand that continues to be priced into the market due to congestion risk. The forward electricity prices for the 2027-2031 calendar strips were 2% higher over the past week, with lower prices seen for 2027/28 terms and higher prices for the later terms 2029/31. The preliminary, day-ahead settlement price for October in COMED is $52.31/MWh or is 10% higher than September’s final settlement price average, while that price average in AdHub is $63.72/MWh or is 1% higher than September. In Michigan the preliminary final, price average for October is $55.03/MWh or is -4% lower than September’s final settlement price average, while in Ameren the price averaged $49.44/MWh or is -16% lower than the prior month’s final average price.
- PJM Submits Revisions to FERC on the Reliability Backstop Procurement (RBP) –PJM filed targeted revisions to the RBP mechanism to address concerns raised in FERC’s 9/29 order. The RBP is a one-time procurement mechanism designed to procure additional capacity in response to rapid large load growth across the region and is scheduled to commence on 3/1. In September, FERC largely accepted PJM’s proposed auction mechanics but raised concerns about cost allocation, transmission owner exit provisions, and load serving entities (LSEs) collateral requirements, inviting PJM to make changes in a further filing. In its new filing, PJM proposes to allocate RBP costs based on incremental large load growth between the 2026 actual summer peak and updated forecast 2028/29 peak; reduce the LSE collateral requirement from the previously proposed $1.5 million/MW to 40% of the net present value of total RBP payment obligations (up to $686,000/MW, if the RBP clears at the $555/MW-day weighted-average price cap); and require LSEs, rather than withdrawing transmission owners, to remain responsible for RBP charges after a transmission owner withdraws from PJM.


Northeast Energy Summary
- On October 7, the Connecticut Public Utilities Regulatory Authority (PURA) issued its final decision in Docket 12-06-02RE05 which sets a 20% non-binding target for spot market purchases to serve default service load. The docket follows recent legislation which requires the utilities to engage in “dynamic market purchases,” including spot market purchases, to serve part of the standard service load. PURA rationalized that the non-binding nature of the target allows the electric distribution companies (EDCs) to reduce the amount of spot market purchases when warranted and further directed its procurement manager to draft criteria and methodology to determine when and to what extent dynamic market purchases would be used. PURAs final decision notes that the inherent portfolio mitigates risk such that no additional risk mitigation is needed for dynamic market purchases up to 20%. However, if the EDCs decide to use more than 20% of dynamic market purchases, they will also need to submit additional risk mitigation techniques for approval. The procurement manager must file an amended procurement plan consistent with the final order by February 1,2027, then the EDCs must file their implementation plans with milestones, cost estimates, and the earliest procurement cycle they can begin dynamic market purchases within 45 days of the procurement plan filing.
- This broader trend toward greater use of spot-market purchases to service default supply continued last week in Rhode Island when Rhode Island Energy (RIE) filed its proposed 2027 Last Resort Service Procurement Plan on October 23. The proposal would increase RIE’s use of spot-market purchases from 15% to 25% of load and correspondingly reduce the amount served by full requirements service contracts from April through September of each year. RIE’s filing estimates that customers would have saved $5.64 million had the additional 10% spot-market exposure been in place since 2016 and contends that the change would allow customers to benefit from favorable summer market conditions while retaining price stability and risk mitigation through full requirements contracts. RIE has requested approval of the plan by January 1, 2027.
- NYISO Management Committee Approves Large Load Proposal Responding to FERC Show Cause Order - On 10/28, stakeholders approved NYISO’s proposal for large and co-located loads in response to FERC’s Show Cause Order, with a roll-call vote of 100% in favor and numerous abstentions. Board action is expected in November, followed by a planned 11/16 Section 205 filing with FERC. The proposal seeks to accelerate load and generator interconnection, strengthen transmission security and resource adequacy studies, and prevent cost shifts by ensuring large loads pay for the network upgrades they cause, particularly in co-location arrangements. NYISO described its consumer protections as shielding customers from unnecessary market costs and improving interconnection cost transparency.
- To address potential resource adequacy impacts, the Large Load Integration Procedures (LLIP) proposal approved Wednesday requires large loads of 50 MW or more to bring corresponding new capacity or face curtailment. Non-Firm Withdrawal Service also caps energy market bids at $200/MWh, effectively curtailing those loads when the transmission system is constrained. The proposal also imposes stricter metering, telemetry, and remote-control requirements on Large and Co-Located Loads, including remote disconnect capability, a ramp-rate limit of 100 MW per five minutes, and a system-wide Large Load Ramp Rate still to be determined. The proposal does not specifically address Load-Contingent New Capacity at Existing Plants.
- The proposal also includes a mechanism that the state could use to exempt a specified large load from the new requirements, developed in response to Department of Public Service staff and stakeholder feedback. Exemptions cannot cause a resource adequacy violation in the first five years of the planning horizon, and exempt projects must still complete NYISO’s study process and transmission security tests. Eligibility will be determined through the Public Service Commission’s ongoing Large Load proceeding (Case 26-E-0045). In the interim, all projects remain subject to the standard NYISO process.
- NYISO Reliability Needs Assessment Advances, Identifies Shortfalls Starting in 2032 - On 10/28, the NYISO Management Committee approved the 2026 Reliability Needs Assessment (RNA), identifying three reliability needs within the 10-year planning horizon and translating years of warnings into actionable findings. New York City’s summer shortfall begins at 400 MW for 7 hours in 2032 and reaches 1,850 MW for 15 hours by 2036. The Hudson Valley’s summer shortfall grows from 130 MW for 2 hours in 2032 to 1,950 MW for 7 hours by 2036. A separate statewide resource deficiency begins at 225 MW in 2033 and exceeds 1,850 MW by 2036.
- The RNA assumes 6,200 MW of new solar, wind, and storage enters service through 2036; New York Power Authority’s roughly 517 MW of small New York City peaker plants retire in 2031 under the 2023 Build Public Renewables law; and 5,400 MW of gas units without firm fuel contracts are unavailable in winter. It includes 2,700 MW of new large loads but excludes more than 12,000 MW of additional large loads in NYISO’s interconnection queue, primarily AI data centers. The assessment also reflects reduced emergency import support as neighboring regions face tighter conditions, along with ongoing risks from New York’s aging fossil fleet.
- NYISO’s independent market monitor, Potomac Economics, says state policy uncertainty has narrowed reliability margins and prompted more conservative planning assumptions. It warns that unresolved fossil plants sitting and permitting policies could impede the most economic solutions. Potomac estimates that addressing the identified reliability needs with new fossil generation would cost about $400 million annually by 2036, compared with about $900 million for batteries alone. The Hochul Administration has signaled openness to new gas generation for reliability under the governor’s “all of the above” energy strategy, potentially supporting new fossil generation over the long term.
- The RNA next goes to the NYISO Board for approval. NYISO will rerun the analysis to incorporate any changes to key inputs and, if reliability needs persist, issue a solicitation for solutions, expected in spring 2027.


ERCOT Energy Summary
- Houston experienced temperatures last week that saw daytime highs get to the mid 80’s but the rest of Texas was in the 70’s. Wind was strong last week, with the exception of Halloween when it averaged only 2.4 GW on a flat average basis. Solar was mostly 6-7 GW on a flat average basis with only Friday (30th) seeing any significant cloud cover.
- As we start November a line of storms moves through the region this morning and afternoon. The storms will be followed by milder weather, with temperatures closer to normal for this time of year. This brings milder days and some cooler nights as we move into a low-demand period that lasts through next week, despite a gradual warming trend. The models are more mixed the following week, with the American operational run allowing below-normal temperatures by the middle weekend of November, while the rest of the model suite shows above-normal temperatures—warm, but not hot.
- Turning to renewables, wind generation will drop from 14 GW on a flat average basis for November 5th to ~6 GW for November 6th through the 9th. Sunny skies will keep solar generation will remain consistent at 6 GW on flat average basis.
- Over the past week ending 10/31, forward prices in ERCOT prices declined ~2 % for 2027, -1.1% for 2028 and 0.5% for 2029. Mild weather remains the biggest short-term driver.
ERCOT Real Time Prices


Source: ERCOT
- Real time prices were pretty quiet overall, not getting above $100/MWh very often. The low wind output on October 31st saw prices reach $120/MWh. On November 2nd prices in the Houston zone hit $120/MWh in HE 16 (3-4 pm CT), likely on congestion or a plant in the Houston zone tripping offline.
Recent Solar, Wind and Battery Milestones:
- There have been no new records set in ERCOT over the past month. ERCOT notched another new battery CHARGING record of 12,299 MW on September 10th at 9:15 am CT, displacing the one from September 1st of 11,460 MW. The discharge record from August 23rd of 13,255 MW at 7:45 pm CT still stands.
- The solar output record of 35,281MW from 7/30 still stands. This surpassed another record set on July 27th for 34,700 MW. The top 10 days for ERCOT maximum solar have occurred so far this year in July and August.
- The new all-time maximum load record of 91,089 MW from July 22nd still stands but August has traditionally seen ERCOT set its new peak loads. ERCOT set a new maximum solar output record 35,281 MW on July 30th and the second new one this week. On July 8th ERCOT set a new discharge record for batteries of 11,674 MW breaking the record of 10,372 MW set back on March 13th.
- June 25th saw a new record output for combined renewables of 51,974 MW, the second this week and breaking the previous record of 47,919 MW on May 14th. ERCOT set a new wind record last week at 28,928 MW on May 17th at 11:50 PM CT as winds were strong overnight. The previous maximum wind record of 28,715 MW set on 3/14 at 10:55 pm CT. ERCOT also set a maximum renewables output of 47,919 MW on May 14th at 3:15 pm CT. This was ~900 MW higher than the previous record from last June.
Generator Outages
- Thermal generation outage levels are in full swing as we start November. Outages have been holding steady 25 -30 GW level in October and this will continue in November until units start to come back.

https://www.gridstatus.io/graph/ercot-outages?iso=ercot&outageType=thermal
Source: ERCOT & Grid Status
TX Legislature, PUCT, & ERCOT News:
PUCT Advances Standard Large Load Interconnection Agreement as SB 6 Implementation Continues - The Public Utility Commission of Texas (PUCT) is preparing to publish a draft Standard Large Load Interconnection Agreement rule that would establish a uniform contract for all large load customers interconnecting in ERCOT. The proposal represents a major step in implementing Senate Bill 6 and would standardize customer obligations related to interconnection costs, financial security, project milestones, operational disclosures, and minimum billing demand requirements. The agreement is intended to create a consistent framework for transmission and distribution level interconnections while incorporating related cost recovery provisions being developed in the Commission’s parallel large-load tariff rulemaking.
The draft expands the obligations placed on large load customers, particularly data centers and other high-demand facilities. Customers would be required to provide extensive disclosures regarding site control, affiliated entities, water usage, permitting status, phased energization schedules, backup generation, power supply arrangements, and potential competing interconnection requests. The agreement also introduces stronger enforcement tools, including audit authority, financial security requirements, transmission-capacity reallocation provisions for delayed projects, and cost recovery mechanisms designed to reduce the risk of stranded infrastructure investments.
PUCT staff recommends publication of the proposal with comments and hearing requests due by 12/14. The PUCT will seek stakeholder feedback on topics including assignment restrictions, treatment of municipal and cooperative utilities, interconnection configuration requirements, metering provisions, and insurance standards.
Batch 1 and Comprehensive Transmission Planning (CTP):
At its October 20th CTP workshop ERCOT stated its intent to run a standalone Batch 1+ process and a separate CTP process vs. integrating them together. ERCOT told the group the standalone process will have the drawback of studying the system twice, once in the batch and once in the reliability study. This will all take about 20 months, but it builds on Batch Zero and works with today's tools and staffing. Each cycle would start every 12 months, with a 6-month Batch study, a 60-day commitment window, and a 12-month reliability study, so one actionable transmission plan would be delivered every 12 months.


CAISO, Desert Southwest and Pacific Northwest Energy Summary
- The first week of November is delivering an unseasonably warm start to the month, with weekend weather models locking in warmer trends that could set records across the West. For energy buyers, this means near to above-normal temperatures will dominate the region, keeping residual cooling demand in play. A brief round of stronger warmth is expected to return to SoCal this weekend, driving daytime highs into the mid-80s, while the rest of the state enjoys unseasonably mild conditions in the 50s and 60s. Looking further ahead, market attention is rapidly shifting from autumn heat and wildfire risks toward the growing prospect of a powerful, persistent El Niño-driven winter. Recent forecast guidance places a greater than 90% chance of above-normal precipitation across California from December - February. While this active southern storm track promises much-needed moisture, it also brings the hazardous transition of intense winter rains hitting heat-hardened, fire-damaged watersheds, potentially impacting electrical infrastructure.
- Despite a recent cooling trend easing prompt demand, natural gas spot settles at the PG&E and SoCal gates to the city are maintaining a firm floor. Weekend settles dropped to $3.42 and $3.46 MMBtu respectively, but the market found strong support as regional storage balances remain tight. PG&E has 168.7 Bcf in the tank, roughly 16 Bcf behind last year’s levels, while SoCalGas stands at 104.3 Bcf, about 2.5 Bcf behind last year. Regional pipeline constraints also eased as Pacific Northwest imports into California jumped to 1.706 Bcf/d following the lifting of maintenance restrictions at GTN’s Kingsgate compressor. This allowed both major California storage points to return to net injections, with PG&E building 0.273 Bcf/d and SoCalGas adding 0.334 Bcf/d. Buyers should remain vigilant regarding the long-term impacts of the incoming winter El Niño; increased cloud cover is anticipated to frequently crush midday solar generation, forcing a higher reliance on thermal gas-fired gen to balance the grid.
- In power, the first week of November is bringing mostly clear, sunny skies to SoCal boosting solar output and driving midday power prices lower. However, a widening north-south basis spread is emerging: CAISO's NP15 day-ahead peak price jumped to $54.43 for Tuesday flow, while SP15 settled significantly lower at $39.72, stretching the regional spread to roughly $15. Grid reliability remains under close watch as major baseload resources, including Diablo Canyon Unit 1 (1,160 MW) and Palo Verde Unit 1 (1,400 MW), are locked into scheduled refueling outages until Nov 11. Operating without these critical assets leaves the western grid vulnerable to late-season cooling demand spikes (like this weekend?) forcing gas generators to fill the supply gaps. A data point for the energy geeks that have read this far: generating a massive 4 GW across three reactors, the Palo Verde Generating Station is the only nuclear plant in the U.S. not located near a body of water. Keeping this massive baseload facility cool in the middle of the Desert Southwest is a feat of engineering, accomplished by recycling municipal wastewater from nearby cities.


Stay up-to-date on the latest energy news and information:
Coming soon from Constellation Customer Insights: Help us provide you with greater service by completing our online study later this month. For a limited time, eligible customers can choose to accept an incentive for taking the time to provide feedback.
- Energy Market Intel Webinar - Register for our next market update webinar on Wednesday, November 18 at 2 p.m. ET when the CMG team will provide insights on market factors currently affecting energy prices, such as weather, gas storage and production, and domestic and global economic conditions.
- Fortunato & Friends Webcast - Stay tuned for information regarding our next Fortunato & Friends webinar featuring Constellation's Chief Economist and a special guest
- Energy Terms to Know - Learn important power, gas and weather terms.
- Sustainability Assessment - We invite you to complete a brief assessment that helps us learn where your company is in building and/or implementing a sustainability plan. Through these insights, Constellation can customize solutions to meet your needs.
- Subscription Center - Sign up to receive updates on the latest market trends.
Questions? Please reach out to our Commodities Management Group at CMG@constellation.com.